Compound Interest: The Most Powerful Force in Investing
Compound interest is why starting early is more important than investing large amounts, and why time in the market consistently outperforms timing the market. Understanding how compounding works gives you the motivation to act decisively on the most powerful force in long-term wealth building.
Albert Einstein may or may not have called compound interest the eighth wonder of the world, but whoever said it was onto something. Compounding is the process by which investment returns generate their own returns, creating growth that accelerates over time in a way that feels counterintuitive until you see the numbers.
The mathematics of compounding is straightforward but its implications are profound. A small amount invested early grows to a larger sum over 40 years than a large amount invested 20 years later. The calendar is your most powerful investment tool, more powerful than any investment strategy, any fund selection, or any market timing.
This guide explains how compounding works mechanically, demonstrates its power through specific examples, and identifies the practical implications for how to approach investing at every stage of life.
How Compound Interest Works
Simple interest generates returns only on the original principal. If you deposit $10,000 at 7 percent simple interest, you earn $700 every year, always calculated on the original $10,000. After 30 years, you have $10,000 plus $21,000 in interest, totaling $31,000.
Compound interest generates returns on both the principal and all previously accumulated returns. With the same $10,000 at 7 percent compounded annually, your balance grows to $76,123 after 30 years. The difference between $31,000 and $76,123 is not a rounding error or a trick; it is the compounding effect of earning returns on returns, year after year.
The compounding frequency affects the outcome as well. Compounding monthly produces slightly more than compounding annually because returns are reinvested more frequently. Most investment accounts compound continuously in the sense that dividends are reinvested and returns accrue daily, producing the maximum benefit of the compounding effect.
| Starting Amount | Annual Return | Years | Final Value | Total Growth |
|---|---|---|---|---|
| $1,000 | 7% | 10 years | $1,967 | 97% |
| $1,000 | 7% | 20 years | $3,870 | 287% |
| $1,000 | 7% | 30 years | $7,612 | 661% |
| $1,000 | 7% | 40 years | $14,974 | 1,397% |
| $10,000 | 7% | 30 years | $76,123 | 661% |
| $10,000 | 10% | 30 years | $174,494 | 1,645% |
The Time Factor: Why Starting Early Dominates Everything Else
Consider two investors, Sarah and Mike. Sarah invests $5,000 per year starting at age 25 and stops at age 35, having invested $50,000 total. Mike invests $5,000 per year starting at age 35 and continues until age 65, having invested $150,000 total. At 8 percent annual return, Sarah's account grows to approximately $615,000 by age 65. Mike's account grows to approximately $566,000. Sarah invested less than one-third of what Mike invested and still ended up with more money, because her money had 40 years to compound while Mike's had a maximum of 30.
This example illustrates the single most important implication of compounding: the opportunity cost of delay is enormous. Every year you wait to start investing does not just cost you that year's returns; it costs you the compounding of all future returns on that year's investment. Waiting until 35 instead of 25 does not cost you 10 years of returns; it costs you the compounding of 10 years of returns over the subsequent 30 years.
The flip side of this insight is equally powerful. Small, consistent investments made early and held through market cycles produce remarkable wealth over long periods. You do not need to invest large amounts to benefit from compounding; you need to invest consistently and give the process time to work.
The Role of Return Rate: Every Percentage Point Matters
The return rate has an enormous impact on long-term outcomes because small differences in annual return compound dramatically over decades. At 6 percent annual return, $10,000 grows to $57,435 over 30 years. At 8 percent annual return, the same amount grows to $100,627. At 10 percent, it grows to $174,494. The difference between 6 percent and 10 percent over 30 years is not four times as much money but three times as much money, because of how differently those rates compound.
This is why investment costs matter so much. An expense ratio of 1 percent instead of 0.03 percent does not merely reduce your return by 0.97 percent per year; it reduces it by a compounding amount that builds year over year. Over 30 years, a 1 percent annual fee reduces the terminal value of a portfolio by approximately 22 percent compared to a 0.03 percent fee. The compounding of costs works against you the same way the compounding of returns works for you.
Taxes have the same compounding effect on long-term wealth when not properly managed. Paying taxes on investment returns each year in a taxable account reduces the capital available to compound in subsequent years. Tax-advantaged accounts like IRAs and 401ks allow the full pre-tax return to compound, which is one of the primary financial arguments for maximizing contributions to these accounts.
Practical Implications: How to Harness Compounding
Start as early as possible. The mathematics could not be clearer: time is the most powerful variable in the compounding equation, and its value is irreplaceable. A dollar invested at 25 is worth far more than a dollar invested at 35, which is worth far more than a dollar invested at 45. The best time to start was yesterday; the second best time is today.
Reinvest all dividends and capital gains distributions automatically. Every distribution that is not reinvested is a compounding cycle that is permanently lost. Brokerage accounts and retirement accounts typically offer automatic reinvestment as a default setting. Confirm that your accounts are set up this way.
Avoid withdrawing from investment accounts before you need the money. Each withdrawal removes capital that would otherwise compound for years or decades into the future. The money you pull from a retirement account at 40 is not just that amount; it is that amount plus all the compounding it would have produced over the next 25 years.
Final Thoughts
Compound interest is not a financial concept to understand intellectually and then set aside. It is a force that is working either for you or against you at every moment, depending on whether you are investing or carrying high-interest debt. The investors who grasp this deeply, not just analytically but emotionally, are the ones who start early, stay consistent, avoid unnecessary withdrawals, and minimize costs.
The decisions that matter most for long-term wealth are not complicated: start investing now, keep costs low, reinvest dividends, maintain contributions through market cycles, and let time do the work that no investment strategy can replicate.
Compounding rewards patience more generously than any other quality in an investor. Give it time to work.
Frequently Asked Questions
James Okafor
Personal Finance Editor
James Okafor covers personal finance, investing and retirement planning. He focuses on helping everyday readers understand the financial decisions that have the biggest long-term impact on their lives, from building credit to planning for retirement.
More Investing Guides
Asset Allocation: How to Diversify Your Portfolio
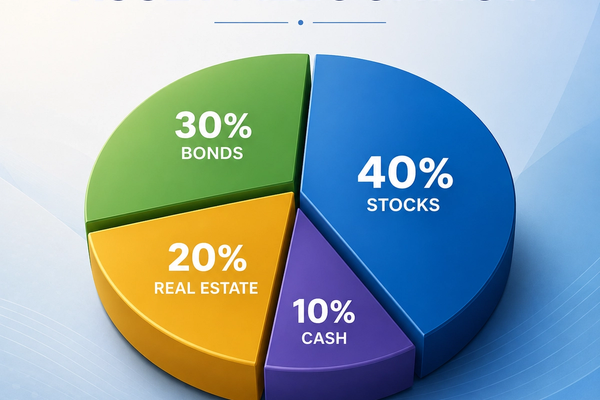
Asset allocation is the single most important investment decision you will make, responsible for more of your long-term returns than any individual stock or fund pick. Understanding how to divide your portfolio across asset classes gives you the foundation of every sound investment strategy.
Best ETFs to Buy for Long-Term Growth
Exchange-traded funds have democratized investing by making it possible to own diversified portfolios at minimal cost. The best ETFs for long-term growth combine broad market exposure, low expense ratios, and the structural simplicity that supports consistent returns over decades.
Bond Investing: What Bonds Are and How to Use Them
Bonds are the portfolio's stabilizer, the ballast that moderates volatility and provides income when stocks are declining. Understanding how bonds work, what drives their returns, and how to use them effectively is essential knowledge for any investor building a complete portfolio.
More Finance Guides Guides
Balance Transfer Credit Cards: How to Use Them to Eliminate Debt
A balance transfer card can be a powerful debt elimination tool when used correctly. Moving high-interest debt to a 0% APR card buys you time to pay off principal without interest accumulating, but the strategy only works if you understand the fees, the timeline, and what happens when the promotional period ends.
Best Personal Loans: How to Find the Right One
Personal loans offer fixed rates, fixed payments, and a defined payoff date that credit cards do not. Finding the best personal loan requires comparing APRs across lenders, understanding origination fees, and matching loan terms to your specific purpose and repayment capacity.

Credit Card Debt: The Fastest Way to Pay It Off
Credit card debt at high interest rates compounds against you every month you carry it. The fastest payoff strategies combine mathematical optimization with behavioral motivation and a clear execution plan that treats the debt elimination as an urgent financial goal.