How to Start Investing: A Beginner's Complete Guide
Starting to invest feels complicated, but the process is more straightforward than most beginners expect. The fundamentals of a sound investment strategy for a beginner can be implemented in an afternoon and maintained with minimal ongoing attention.
The barrier that prevents most beginners from starting to invest is not lack of money or lack of opportunity. It is the perception of complexity: the sense that investing requires specialized knowledge, constant market monitoring, and sophisticated strategy that most people do not have. This perception is almost entirely wrong, and it is costing beginners the most valuable commodity in investing, which is time.
Starting to invest as a beginner is genuinely straightforward when you focus on the fundamentals: open an account, choose simple investments, contribute regularly, and leave them alone. The complexity that financial media, financial advisors, and investing platforms create is largely unnecessary for a beginner building long-term wealth. The most successful long-term investors often follow the simplest strategies.
This complete guide walks a beginner through every step from defining goals to choosing investments to maintaining the portfolio, with specific recommendations appropriate for someone starting from zero.
Step 1: Get Your Financial Foundation Right First
Before investing a single dollar in the market, make sure the financial foundation is solid. This means having at least one to three months of essential living expenses in a liquid, stable savings account (ideally a high-yield savings account earning 4 to 5 percent). Without this buffer, an unexpected expense may force you to sell investments at a loss to cover it.
If you carry high-interest debt, particularly credit card debt above 15 percent APR, paying it off before investing in the stock market is usually the better financial decision. There is no investment that reliably earns more than a 20 percent guaranteed return, which is the equivalent of paying off credit card debt at that rate. Low-interest debt like student loans or car loans presents a more nuanced calculation.
Consider your tax-advantaged options before anything else. If your employer offers a 401k with a match, contributing at least enough to capture the full match is a guaranteed 50 to 100 percent return on the matched dollars, which beats any investment available. This should be the absolute first priority for anyone whose employer offers this benefit.
| Priority Order | Action | Why It Comes First |
|---|---|---|
| 1 | Emergency fund (1-3 months expenses) | Prevents forced selling of investments |
| 2 | 401k to employer match | Guaranteed 50-100% return on matched dollars |
| 3 | High-interest debt payoff (>10%) | Guaranteed return equals the interest rate |
| 4 | Max Roth IRA ($7,000 in 2024) | Tax-free growth over decades |
| 5 | Max 401k beyond match | Tax-advantaged retirement savings |
| 6 | Taxable brokerage account | Additional investing after retirement accounts |
Step 2: Choose the Right Account
For most beginners, a Roth IRA is the best first investment account. Contributions are made with after-tax money, but everything inside grows tax-free and withdrawals in retirement are tax-free. The Roth IRA allows contributions of up to $7,000 per year in 2024, with a phase-out for high earners starting at $146,000 for single filers.
If you are not eligible for a Roth IRA due to income limits, or have already maxed it out, a traditional IRA provides a tax deduction for contributions now and tax-deferred growth. If you have maxed out IRA options, a taxable brokerage account provides additional investing capacity with no contribution limits but no tax advantages.
Open your account at Fidelity, Schwab, or Vanguard. All three are excellent, free to use, and have no minimum balance requirements. Fidelity is often recommended for beginners because of its fractional share investing (allowing any dollar amount), excellent customer service, and comprehensive research tools.
Step 3: Choose Your First Investment
For a beginner who wants to start investing immediately and not spend significant time on investment selection, a target-date fund is the single best first investment. A target-date fund is a one-fund diversified portfolio that automatically adjusts its allocation from aggressive (high stocks) to conservative (more bonds) as the target date approaches. Choose the fund with the year closest to when you plan to retire: Fidelity Freedom 2055 Fund if you plan to retire around 2055.
Alternatively, a three-fund portfolio using index funds is the approach favored by DIY investors who want maximum control at minimal cost: a total US stock market fund, a total international stock fund, and a total bond market fund, allocated based on your age and risk tolerance. This approach provides excellent long-term performance at very low cost and is the portfolio structure recommended by the Bogleheads community.
What to avoid as a beginner: individual stocks (require significant analysis and concentration risk), actively managed funds (higher costs without reliable outperformance), cryptocurrency (extreme volatility inappropriate as a primary investment), and any investment you cannot clearly explain in one sentence.
Step 4: Invest Regularly and Leave It Alone
Set up automatic contributions from your bank account to your investment account on a fixed schedule, ideally monthly, aligned with your paycheck. Automatic contributions implement dollar-cost averaging, maintain investment discipline through market volatility, and remove the decision of when to invest from each month's agenda.
Check your portfolio no more than quarterly. Daily or even monthly portfolio checking creates anxiety without providing useful information and has been shown to correlate with worse investor returns because frequent checking leads to reactive selling during downturns.
Increase your contribution rate whenever your income increases. The financial independence community recommends increasing your savings rate by at least half of any raise. If you get a $5,000 annual raise, direct $2,500 of it to additional investment contributions and spend the other $2,500. This approach gradually increases your investment rate without significantly reducing your lifestyle.
Final Thoughts
Starting to invest is not complicated. It requires a few good decisions made once: open an account, choose a simple investment like a target-date fund or a three-fund portfolio, set up automatic contributions, and leave the portfolio alone to compound over time. The rest, the specific funds, the exact allocation percentages, the rebalancing schedule, are details that can be refined as your knowledge grows.
The most important decision is the first one: to start. Every month of delay is a month of compounding permanently lost. Every month of contribution, no matter how small, builds the habit and the portfolio that will compound into significant wealth over decades.
Start simple. Start now. Stay consistent. The complexity can come later; the time cannot.
Frequently Asked Questions
James Okafor
Personal Finance Editor
James Okafor covers personal finance, investing and retirement planning. He focuses on helping everyday readers understand the financial decisions that have the biggest long-term impact on their lives, from building credit to planning for retirement.
More Investing Guides
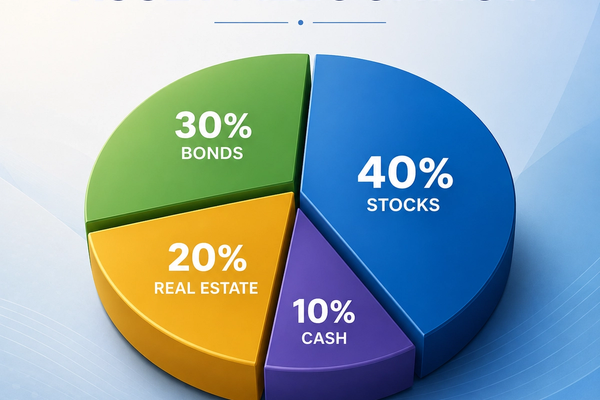
Asset Allocation: How to Diversify Your Portfolio
Asset allocation is the single most important investment decision you will make, responsible for more of your long-term returns than any individual stock or fund pick. Understanding how to divide your portfolio across asset classes gives you the foundation of every sound investment strategy.
Best ETFs to Buy for Long-Term Growth
Exchange-traded funds have democratized investing by making it possible to own diversified portfolios at minimal cost. The best ETFs for long-term growth combine broad market exposure, low expense ratios, and the structural simplicity that supports consistent returns over decades.
Bond Investing: What Bonds Are and How to Use Them
Bonds are the portfolio's stabilizer, the ballast that moderates volatility and provides income when stocks are declining. Understanding how bonds work, what drives their returns, and how to use them effectively is essential knowledge for any investor building a complete portfolio.
More Finance Guides Guides
Balance Transfer Credit Cards: How to Use Them to Eliminate Debt
A balance transfer card can be a powerful debt elimination tool when used correctly. Moving high-interest debt to a 0% APR card buys you time to pay off principal without interest accumulating, but the strategy only works if you understand the fees, the timeline, and what happens when the promotional period ends.
Best Personal Loans: How to Find the Right One
Personal loans offer fixed rates, fixed payments, and a defined payoff date that credit cards do not. Finding the best personal loan requires comparing APRs across lenders, understanding origination fees, and matching loan terms to your specific purpose and repayment capacity.

Credit Card Debt: The Fastest Way to Pay It Off
Credit card debt at high interest rates compounds against you every month you carry it. The fastest payoff strategies combine mathematical optimization with behavioral motivation and a clear execution plan that treats the debt elimination as an urgent financial goal.