Value Investing vs Growth Investing: Which Strategy Is Better?
Value and growth are the two dominant stock investing philosophies, representing different beliefs about where excess returns originate. Neither consistently beats the other in all conditions, and understanding both helps you make intentional choices about the role each plays in a long-term portfolio.
Value investing and growth investing represent fundamentally different theories about where investment returns come from and what drives stock prices. Value investors believe that markets periodically misprice securities, offering opportunities to buy quality companies at prices below their intrinsic value. Growth investors believe that the highest returns come from identifying companies with exceptional growth trajectories and holding them as that growth materializes.
The debate between value and growth is one of the oldest in investing, and both approaches have periods of significant outperformance relative to the other. The 2010s were a dominant decade for growth investing, particularly technology-oriented growth stocks. Value investing dominated the early 2000s and has historically outperformed over very long periods when measured carefully. Neither approach has a permanent, consistent edge in all market conditions.
This guide explains each approach, examines the evidence about their long-run performance, and helps you think about whether either or both belong in your investment strategy.
What Value Investing Is and How It Works
Value investing, most famously articulated by Benjamin Graham and practiced by Warren Buffett, seeks to buy stocks that are trading below their estimated intrinsic value, creating a margin of safety against the uncertainty of future events. The identification of undervalued stocks typically relies on fundamental valuation metrics: low price-to-earnings ratios, low price-to-book ratios, and high earnings yields relative to the market.
The theory underlying value investing is that markets are not perfectly efficient in the short run and that investor psychology creates systematic mispricings. Companies that have experienced bad news, disappointing earnings, or unfashionable industry status may be priced below their fundamental worth because investors overreact to negative developments. The value investor buys these unloved stocks and waits for the market to recognize their true worth.
The challenge of value investing in practice is distinguishing between genuinely cheap stocks and cheap stocks that deserve to be cheap because their fundamental outlook is deteriorating. A low P/E ratio might reflect a bargain or might reflect that the business is structurally declining. The work of value investing is separating value traps from genuine value opportunities.
| Characteristic | Value Investing | Growth Investing |
|---|---|---|
| Focus | Current valuation relative to intrinsic value | Future earnings growth potential |
| Valuation multiples | Low P/E, P/B; high dividend yield | High P/E, P/S; often no dividends |
| Holding period | Medium to long; wait for revaluation | Long; hold through growth phase |
| Primary risk | Value trap; cheap for a reason | Multiple compression; growth disappointment |
| Iconic practitioners | Benjamin Graham, Warren Buffett | Philip Fisher, Peter Lynch |
| Market environment | Performs better in value recoveries, rising rates | Performs better in growth environments, falling rates |
| Academic evidence | Long-run value premium documented | Momentum and quality factors support |
What Growth Investing Is and How It Works
Growth investing focuses on companies that are growing their revenue and earnings significantly faster than the average company, with the expectation that this exceptional growth will drive stock prices higher over time. Growth investors are typically willing to pay premium valuations, including high P/E ratios, for companies whose future earnings potential justifies the current price.
The theoretical basis for growth investing is that the future earnings of exceptional businesses compound at rates that make today's high valuations appear reasonable when viewed over a long horizon. A company growing earnings at 25 percent per year doubles earnings every three years, and the cumulative effect of this compounding over a decade makes a current P/E of 40 potentially reasonable if the growth is sustained.
The risk in growth investing is multiple compression: the stock price declining not because earnings decline but because investors are no longer willing to pay the high valuation premium they previously paid. When growth expectations disappoint or when interest rates rise, making future earnings worth less in present value terms, growth stocks can decline dramatically even when the underlying business is still performing reasonably well.
The Evidence: Long-Run Performance of Value vs Growth
Academic research by Fama and French identified a value premium in US stocks, finding that stocks with low valuations (value stocks) have historically outperformed stocks with high valuations (growth stocks) over long periods. This premium is well-documented over the full century of available data and has been found in most international markets as well.
However, the value premium has been inconsistent and absent for extended periods. US growth stocks significantly outperformed value stocks from roughly 2007 to 2021, a 14-year period that tested the conviction of value investors. The underperformance was so prolonged that some researchers questioned whether the value premium still existed in a world where information asymmetry had been reduced by technology.
The 2022 market correction, driven by rising interest rates, produced a significant reversal: value stocks dramatically outperformed growth stocks for the first time in years. This reversal demonstrated that the value premium, while inconsistent over shorter periods, may persist as a structural feature of market dynamics rather than having disappeared permanently.
Practical Implications: How to Use This in Your Portfolio
For most long-term investors, the most practical implication of the value vs growth debate is that neither factor should dominate a portfolio to the exclusion of the other. A diversified market-cap-weighted index fund holds both value and growth stocks in proportion to their market weight, providing exposure to both approaches without requiring a bet on which will outperform in the near term.
Investors who want to tilt toward value can do so through dedicated value ETFs like VTV (Vanguard Value ETF) or AVUV (Avantis US Small Cap Value), which overweight the value factor. Investors who want growth exposure can tilt toward growth through VUG (Vanguard Growth ETF) or VOOG. Both tilts introduce tracking error relative to the broad market and require conviction that the targeted factor will outperform over the relevant horizon.
The most important principle for either approach is holding period. Value investing requires the patience to hold unloved stocks through extended periods of underperformance as the market reprices them. Growth investing requires the conviction to hold premium-valued stocks through periods of multiple compression. Neither approach delivers its benefits to short-term investors who exit when the strategy is temporarily out of favor.
Final Thoughts
Value and growth investing represent two legitimate but different theories about where investment returns originate. Both approaches have strong intellectual foundations, both have produced exceptional investors when practiced with skill and discipline, and neither consistently dominates the other across all market conditions.
For most investors, the practical conclusion is straightforward: a broad market index fund captures both value and growth exposure at minimal cost, provides exposure to both factor premiums when they appear, and requires neither the research capability to identify genuine value opportunities nor the forecasting ability to identify exceptional growth companies.
If you want to tilt toward one or the other, do so deliberately with full understanding of the tracking error you are accepting and the conviction required to maintain the tilt through extended periods of underperformance. Factor investing rewards patience and penalizes abandonment at exactly the wrong moments.
Frequently Asked Questions
James Okafor
Personal Finance Editor
James Okafor covers personal finance, investing and retirement planning. He focuses on helping everyday readers understand the financial decisions that have the biggest long-term impact on their lives, from building credit to planning for retirement.
More Investing Guides
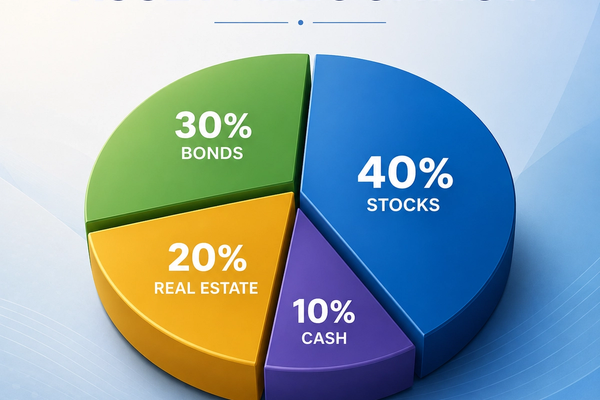
Asset Allocation: How to Diversify Your Portfolio
Asset allocation is the single most important investment decision you will make, responsible for more of your long-term returns than any individual stock or fund pick. Understanding how to divide your portfolio across asset classes gives you the foundation of every sound investment strategy.
Best ETFs to Buy for Long-Term Growth
Exchange-traded funds have democratized investing by making it possible to own diversified portfolios at minimal cost. The best ETFs for long-term growth combine broad market exposure, low expense ratios, and the structural simplicity that supports consistent returns over decades.
Bond Investing: What Bonds Are and How to Use Them
Bonds are the portfolio's stabilizer, the ballast that moderates volatility and provides income when stocks are declining. Understanding how bonds work, what drives their returns, and how to use them effectively is essential knowledge for any investor building a complete portfolio.
More Finance Guides Guides
Balance Transfer Credit Cards: How to Use Them to Eliminate Debt
A balance transfer card can be a powerful debt elimination tool when used correctly. Moving high-interest debt to a 0% APR card buys you time to pay off principal without interest accumulating, but the strategy only works if you understand the fees, the timeline, and what happens when the promotional period ends.
Best Personal Loans: How to Find the Right One
Personal loans offer fixed rates, fixed payments, and a defined payoff date that credit cards do not. Finding the best personal loan requires comparing APRs across lenders, understanding origination fees, and matching loan terms to your specific purpose and repayment capacity.

Credit Card Debt: The Fastest Way to Pay It Off
Credit card debt at high interest rates compounds against you every month you carry it. The fastest payoff strategies combine mathematical optimization with behavioral motivation and a clear execution plan that treats the debt elimination as an urgent financial goal.