Health Care Costs in Retirement: How to Plan and Save
Healthcare is the largest and most unpredictable expense in retirement. Understanding what Medicare covers, what it does not, and how to save specifically for healthcare costs through HSAs and supplemental insurance prevents one of the most common retirement financial crises.
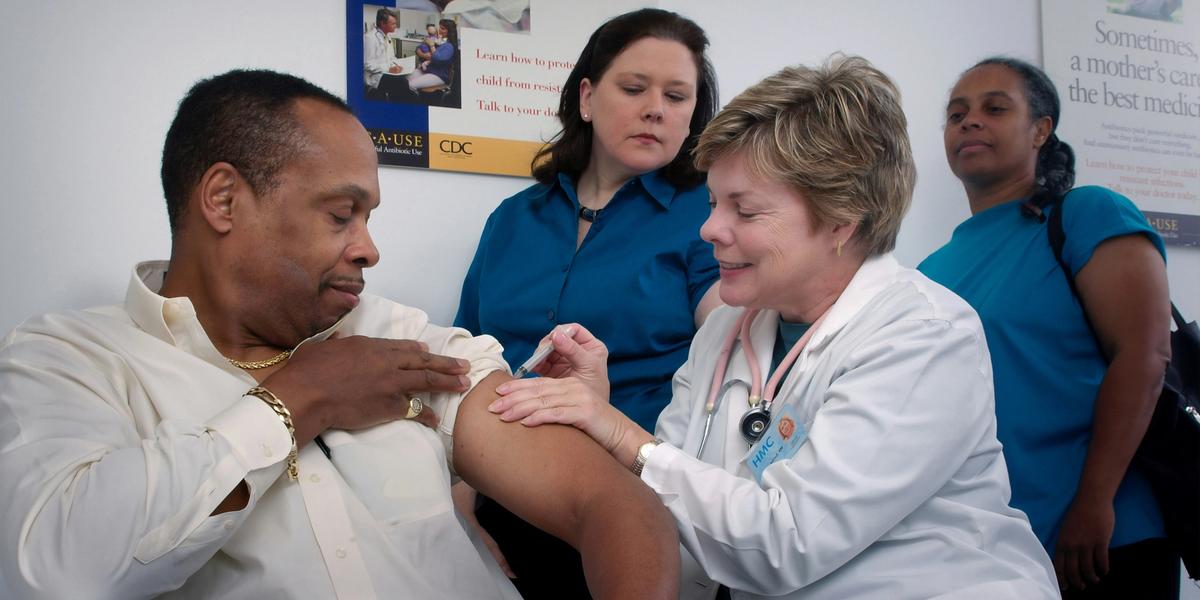
Healthcare costs are consistently underestimated in retirement planning, and the consequences of that underestimation are severe. Fidelity Investments estimates that a 65-year-old couple retiring today will need approximately $315,000 to cover healthcare costs in retirement, not including long-term care. This figure assumes Medicare coverage and represents out-of-pocket costs: premiums, deductibles, copayments, and expenses for services Medicare does not cover.
Medicare is the primary health insurance for Americans 65 and older, but it is not free and it does not cover everything. Premiums, dental care, vision care, hearing aids, and prescription drug costs not covered by Part D are all out-of-pocket expenses that retirees must budget for. Many retirees are shocked by the ongoing cost of Medicare coverage, particularly when their income is higher and triggers the IRMAA surcharge on Part B and Part D premiums.
This guide explains how to plan realistically for retirement healthcare costs, how to use health savings accounts to build a dedicated healthcare reserve, what Medicare does and does not cover, and how to evaluate supplemental coverage options.
What Medicare Covers and What It Does Not
Medicare Part A covers inpatient hospital care, skilled nursing facility care following a qualifying hospital stay, hospice care, and some home health services. Most people receive Part A premium-free because they or their spouse paid Medicare taxes for at least 40 quarters of employment.
Medicare Part B covers outpatient medical services, physician visits, preventive care, medical equipment, and most non-hospital medical services. Part B has a monthly premium ($174.70 standard in 2024), an annual deductible, and 20 percent coinsurance after the deductible, with no annual out-of-pocket maximum for beneficiaries without supplemental coverage.
Medicare does not cover routine dental care, vision care, hearing aids and examinations, long-term custodial care in a nursing home or at home, most care received outside the US, and many other services that retirees commonly need. These gaps are significant and require planning through supplemental coverage, dedicated savings, or Medicare Advantage plans that include some of these benefits.
| Healthcare Cost Category | Medicare Coverage | Out-of-Pocket Exposure |
|---|---|---|
| Hospital stays (Part A) | Covered after deductible ($1,632/benefit period 2024) | Deductible plus coinsurance for long stays |
| Physician and outpatient services | 80% after Part B deductible | 20% coinsurance; no annual cap without Medigap |
| Prescription drugs (Part D) | Covered with enrollment in Part D plan | Premiums, deductibles, copays; gap coverage |
| Dental care | Not covered | 100% out of pocket unless supplemental insurance |
| Vision care | Not covered (eye disease covered) | 100% for routine vision and glasses |
| Hearing aids | Not covered | 100% out of pocket; significant cost |
| Long-term care | Limited; only short-term skilled nursing | Largest uninsured retirement healthcare cost |
The Health Savings Account: The Best Retirement Healthcare Vehicle
A Health Savings Account paired with a qualifying high-deductible health plan is the most powerful tool available for pre-funding retirement healthcare costs. Contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free, creating the only triple-tax-advantaged account in the US tax code.
HSA funds can be used for any qualified medical expense tax-free, including Medicare premiums (Part B, Part D, Medicare Advantage), dental and vision costs, long-term care insurance premiums, and thousands of other medical expenses. The list of qualified expenses is broad and specifically designed to cover what Medicare does not.
The most powerful HSA strategy for those who can execute it is to contribute the maximum annually while paying current medical costs out of pocket, investing the HSA balance in equities, and allowing the balance to compound tax-free over decades. A 30-year-old who maximizes an HSA contribution of $4,150 annually (for self-only coverage in 2024) and invests the balance in a stock index fund would accumulate approximately $500,000 by retirement age at historical market returns, all available tax-free for healthcare.
Medicare Supplement and Medicare Advantage: Bridging Coverage Gaps
Medigap (Medicare Supplement) policies cover cost-sharing under Original Medicare, including the 20 percent Part B coinsurance, the Part A deductible, and in some plans, excess charges from providers who accept Medicare but do not participate. Plan G is currently the most comprehensive Medigap option available to new enrollees, covering virtually all Medicare cost-sharing except the Part B deductible.
Medicare Advantage (Part C) plans are private insurance alternatives to Original Medicare that bundle Parts A and B and usually Part D into a single plan, often with additional benefits including dental, vision, hearing, and fitness benefits not covered by Original Medicare. Medicare Advantage plans typically have lower premiums than Original Medicare plus Medigap but use provider networks and may require prior authorization for services.
The choice between Original Medicare plus Medigap and Medicare Advantage is one of the most consequential healthcare coverage decisions for retirees. Original Medicare plus Medigap provides the broadest provider access with the most predictable costs. Medicare Advantage provides additional benefits at lower premiums but with network restrictions and administrative requirements that some beneficiaries find limiting.
Long-Term Care: The Largest Unplanned Healthcare Cost
Long-term care, including custodial care in a nursing home, assisted living facility, or at home, is not covered by Medicare except for short-term skilled nursing care following a qualifying hospital stay. The average cost of a private room in a nursing home is approximately $100,000 per year. The average length of long-term care need is approximately two to three years, though some individuals require care for much longer.
Long-term care insurance provides coverage for custodial care costs that Medicare and standard health insurance do not cover. Traditional long-term care insurance policies have become expensive and less available as insurers have exited the market due to underpricing in earlier years. Hybrid policies that combine life insurance or annuities with long-term care benefits are now more commonly available.
Medicaid is the payer of last resort for long-term care for those who have spent down their assets to the Medicaid eligibility threshold. Planning for this scenario, either through long-term care insurance, self-insurance through dedicated savings, or Medicaid planning with an attorney, should be part of every comprehensive retirement financial plan.
Final Thoughts
Healthcare costs are the largest planning variable in retirement, affecting both the total amount you need to save and the security with which you can spend in retirement. Planning for these costs with realistic estimates rather than assuming Medicare covers everything is essential for avoiding the financial disruption that unexpected healthcare costs create.
The health savings account is the most powerful pre-retirement tool for addressing this challenge. Maximize it annually if you have access to a qualifying high-deductible health plan. Invest the balance in equities for long-term growth. Save receipts for current medical expenses to preserve the option of future reimbursement.
Healthcare in retirement is manageable with the right planning. It is a crisis without it.
Frequently Asked Questions
James Okafor
Personal Finance Editor
James Okafor covers personal finance, investing and retirement planning. He focuses on helping everyday readers understand the financial decisions that have the biggest long-term impact on their lives, from building credit to planning for retirement.
More Retirement & Savings Guides
401k vs IRA: Which Retirement Account Is Better?
The 401k and IRA are the two most important retirement savings vehicles for most Americans, and they are not mutually exclusive. Understanding how they differ, how they complement each other, and which to prioritize in what order maximizes the tax advantages available to you.
529 College Savings Plans: A Complete Guide
A 529 plan is the most tax-advantaged way to save for education expenses. Understanding how contributions grow tax-free, which expenses qualify, what happens if the beneficiary does not attend college, and the new rollover rules makes 529s more flexible than most families realize.
Backdoor Roth IRA: How High Earners Can Access Roth Benefits
High earners above Roth IRA income limits can still access Roth's tax-free growth through the Backdoor Roth IRA strategy. Understanding the mechanics, the pro-rata rule, and how to execute the conversion cleanly is essential before attempting this strategy.
More Finance Guides Guides
Balance Transfer Credit Cards: How to Use Them to Eliminate Debt
A balance transfer card can be a powerful debt elimination tool when used correctly. Moving high-interest debt to a 0% APR card buys you time to pay off principal without interest accumulating, but the strategy only works if you understand the fees, the timeline, and what happens when the promotional period ends.
Best Personal Loans: How to Find the Right One
Personal loans offer fixed rates, fixed payments, and a defined payoff date that credit cards do not. Finding the best personal loan requires comparing APRs across lenders, understanding origination fees, and matching loan terms to your specific purpose and repayment capacity.

Credit Card Debt: The Fastest Way to Pay It Off
Credit card debt at high interest rates compounds against you every month you carry it. The fastest payoff strategies combine mathematical optimization with behavioral motivation and a clear execution plan that treats the debt elimination as an urgent financial goal.