Best Life Insurance for Smokers
Smokers pay significantly higher life insurance premiums than non-smokers, but the spread between the best and worst available rates is substantial. Knowing which companies offer the most competitive smoker rates, what counts as smoking for underwriting purposes, and how quitting affects your premium helps you find the best available coverage.
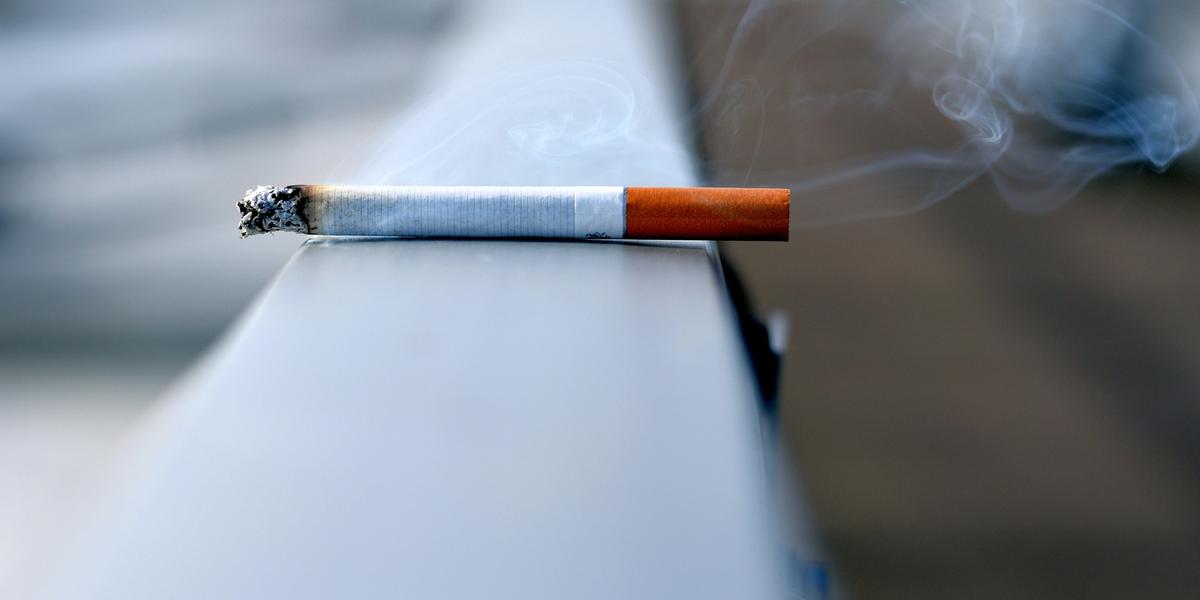
Life insurance underwriting reflects the statistical reality that smokers have significantly higher mortality rates than non-smokers. This is not discriminatory in the insurance sense; it is actuarially sound. The premium difference between smoker and non-smoker rates at most insurers is substantial, often two to three times the non-smoker premium for the same coverage amount and term.
Within the smoker category, however, there is meaningful variation. Different insurers weigh tobacco use differently, classify different products differently, and offer different premium levels that make the spread between the best and worst available smoker rates quite significant. For a smoker seeking coverage, this variation is an opportunity that comparison shopping can capture.
This guide explains how smoker classification works, which companies offer the most competitive rates for tobacco users, how different tobacco products are treated, and what the path looks like from smoker to non-smoker pricing when you quit.
How Life Insurers Define and Rate Tobacco Use
Life insurance underwriting classifies tobacco use broadly and consistently across the industry. Any form of nicotine use within the past 12 months, sometimes extended to 24 months, results in smoker classification for most insurers. This includes cigarettes, cigars, pipe tobacco, chewing tobacco, snuff, nicotine patches, nicotine gum, vaping and e-cigarettes, and in most cases nicotine replacement products used as cessation aids.
The method of testing is cotinine screening in blood or urine, which detects nicotine metabolites with high accuracy. Applicants who answer non-smoker on their application but test positive for cotinine face policy rescission for material misrepresentation, which eliminates coverage entirely. Honest disclosure of tobacco use, while resulting in higher premiums, is the only approach that actually produces coverage.
Some insurers have separate rating classes for different tobacco products. Cigars smoked occasionally, sometimes defined as fewer than one per week or fewer than 12 per year, may qualify for non-smoker or preferred non-smoker rates at some carriers. Smokeless tobacco users may also receive slightly more favorable treatment than cigarette smokers at some companies. These distinctions are carrier-specific and worth exploring for occasional cigar smokers specifically.
| Tobacco Product | Typical Rating | Exceptions |
|---|---|---|
| Cigarettes (current) | Standard tobacco rate | No exceptions at most carriers |
| Cigars (occasional) | Varies; some non-smoker exceptions | Some carriers allow 12 or fewer per year as non-smoker |
| Pipe tobacco | Tobacco rate | Same as cigarettes at most carriers |
| Chewing tobacco / snuff | Tobacco rate | Same as cigarettes at most carriers |
| Vaping / e-cigarettes | Tobacco rate at most carriers | Some carriers treat differently; evolving |
| Nicotine patches / gum | Tobacco rate | Testing positive for cotinine triggers smoker rating |
Which Companies Offer the Most Competitive Smoker Rates
Smoker rates vary significantly between carriers because different actuarial assumptions, different target markets, and different competitive strategies produce different pricing decisions for the tobacco user category. Some carriers price smoker coverage attractively because they want to grow this market segment; others price it at the high end because they have less appetite for tobacco risk.
Prudential, Pacific Life, and Protective Life are frequently cited by independent life insurance brokers as among the more competitive carriers for smoker rates on term life insurance. The premium difference between these companies and higher-priced alternatives for the same smoker, same term, and same coverage amount can be meaningful enough to save thousands of dollars in premium over a 20-year term.
Working with an independent life insurance broker who has access to 20 or more carriers is the most efficient way to find competitive smoker rates. These brokers can submit your profile to multiple carriers simultaneously through a quote comparison process and identify who is currently pricing most aggressively for your specific age, health profile, and smoking history.
The Quit Date: When Smoker Rates Change to Non-Smoker
The most impactful premium improvement available to a current smoker is quitting and then waiting the required period to qualify for non-smoker rates. Most life insurers require that an applicant have been completely tobacco-free for 12 months before classifying them as a non-smoker. Some carriers require 24 months of abstinence. A few require five years of tobacco-free status for their best preferred non-smoker rates.
The premium reduction when reclassified from smoker to non-smoker is dramatic because the rate classes are so different. A 40-year-old male who is classified as a smoker might pay $150 per month for a 20-year term policy. Reclassified as a non-smoker after 12 months of abstinence, the same policy might be reissued at $55 per month. That difference compounds over a 20-year term to a premium saving of $22,800.
The practical implication is that smokers who are considering quitting have a specific and large financial incentive to do so from an insurance cost perspective. Purchasing a shorter-term policy now while smoking, with a plan to convert or replace it with non-smoker coverage after 12 months of abstinence, is a strategy that some brokers recommend for smokers who are actively working toward cessation.
Guaranteed Issue and Simplified Issue Options for Smokers
Smokers who face additional health conditions beyond tobacco use may find standard underwritten life insurance difficult to qualify for at any price. Guaranteed issue life insurance, which requires no medical examination and asks no health questions, is available to anyone within the eligible age range regardless of health status. The trade-off is lower coverage amounts, typically $5,000 to $25,000, and higher premiums relative to coverage than standard policies.
Simplified issue policies ask health questions but require no medical examination. They offer more coverage than guaranteed issue, sometimes up to $500,000, and lower premiums, but they do ask about tobacco use and other health conditions. A smoker with otherwise good health may find simplified issue policies competitive for modest coverage amounts without the inconvenience of a medical exam.
For smokers who are otherwise healthy and seeking significant coverage amounts, fully underwritten policies remain the best value despite the smoker surcharge. The premium savings from underwritten coverage relative to simplified or guaranteed issue are substantial for large coverage amounts, and the medical exam process is not particularly burdensome for applicants in good health beyond the smoking habit.
Final Thoughts
Life insurance for smokers is more expensive than for non-smokers, but it is available and it is worth having. The range of prices in the smoker market is significant enough that comparison shopping through an independent broker can produce meaningful savings relative to simply accepting the first quote received.
The most powerful long-term strategy is quitting. The financial incentive from life insurance premium savings alone is substantial, and the health benefits compound that incentive many times over. If you are working toward cessation, the 12-month mark when non-smoker rates become available is a significant milestone worth anticipating.
Get covered at the best available smoker rate today. Work toward the non-smoker rate that quitting makes available tomorrow.
Frequently Asked Questions

Rebecca Torres
Insurance Editor
Rebecca Torres has covered the insurance industry for nearly a decade, focusing on helping consumers understand their coverage, navigate claims and avoid the costly mistakes that come from misunderstanding policy terms.
More Insurance Comparisons Guides
Best Boat and Watercraft Insurance Compared
Boat insurance is not required in most states, but it protects against risks that no responsible watercraft owner should leave unaddressed. Here is how the leading boat insurance companies compare and what to look for in a policy.
Best Insurance Companies for Claims Service
A low premium means nothing if your insurer fails you when you need to file a claim. The companies with the best claims service combine fast response, fair settlements, and clear communication. Here is how the leading insurers rank where it actually matters.
Best Insurance for High-Value Homes
Standard homeowner's insurance is designed for average homes at average values. High-value homes require a different kind of coverage: higher limits, broader perils, better claims service, and insurers who understand what restoration of distinctive architecture and premium finishes actually costs.
More Insurance Guides Guides

Best Car Insurance Companies Ranked and Compared
The best car insurance company for you is not necessarily the biggest one or the cheapest one. It is the one that balances competitive pricing, genuine coverage quality, and claims service you can rely on when it actually matters. Here is how the leading companies stack up on all three.

Car Insurance After an Accident: What Happens to Your Rates
After an accident, your car insurance company will almost certainly reassess your risk profile, and your premium will likely increase at renewal. Understanding how much rates typically rise, how long the impact lasts, and what you can do to minimize the damage gives you a realistic picture of what comes next.

Car Insurance Discounts You Might Be Missing
Most car insurance policyholders leave money on the table every year by not claiming every discount they qualify for. Some discounts require nothing more than asking; others require simple actions that take minutes but produce savings that compound year over year.